Dr Mike Derksen appointed Honorary Fellow at the KdVI
Mathematics and Statistics for Financial Markets
12 October 2026
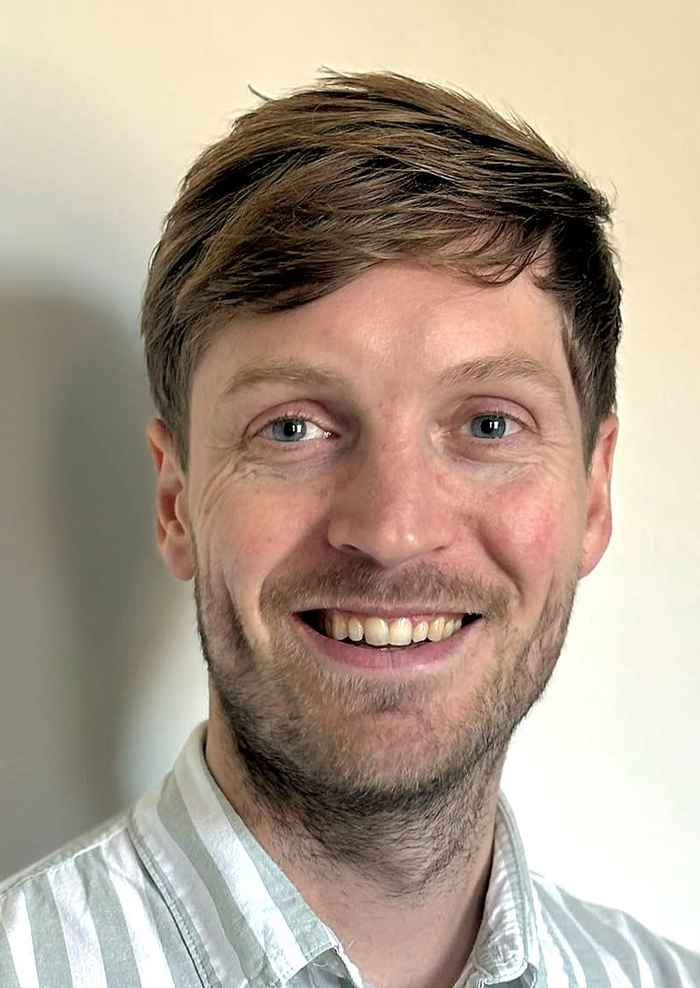
Mike Derksen is involved in the development and analysis of quantitative models for financial markets, with applications in automated trading and statistical arbitrage. Based on his experience in financial practice, he investigates, how large amounts of data can be used to better model and understand financial markets. By testing models against real market data, he connects theoretical insights with practical applications in the financial sector. His research is at the intersection of mathematics, statistics and financial markets.
In this role, he strengthens the connection between KdVI and Deep Blue Capital, a quantitative trading organization focused on the development and application of automated trading strategies in financial markets.
Mike Derksen holds a PhD in Financial Mathematics from the University of Amsterdam and works as a Senior Quantitative Trading Developer at Deep Blue Capital. He has extensive experience in the development and implementation of quantitative methods for financial markets, with applications in statistical arbitrage, automated trading and risk management, among others. In addition, he has been closely involved in education at the UvA for many years, including as a lecturer within the Bachelor's programme in Mathematics and as a regular guest speaker in the Master's programme in Stochastics and Financial Mathematics.